Tycheon
Kronos forecasts the path; Tycheon tells you how much to trust it.
Tycheon is the open-source calibrated forecasting and risk layer for financial time series: conformal prediction intervals you can check, exogenous covariates beyond OHLCV, regime-weighted routing across Kronos, TimesFM, Chronos and honest baselines, translation of forecasts into VaR, Expected Shortfall and drawdown probabilities, and leakage-proof walk-forward evaluation with a public leaderboard.
v0.1.0 - evidence so far is synthetic
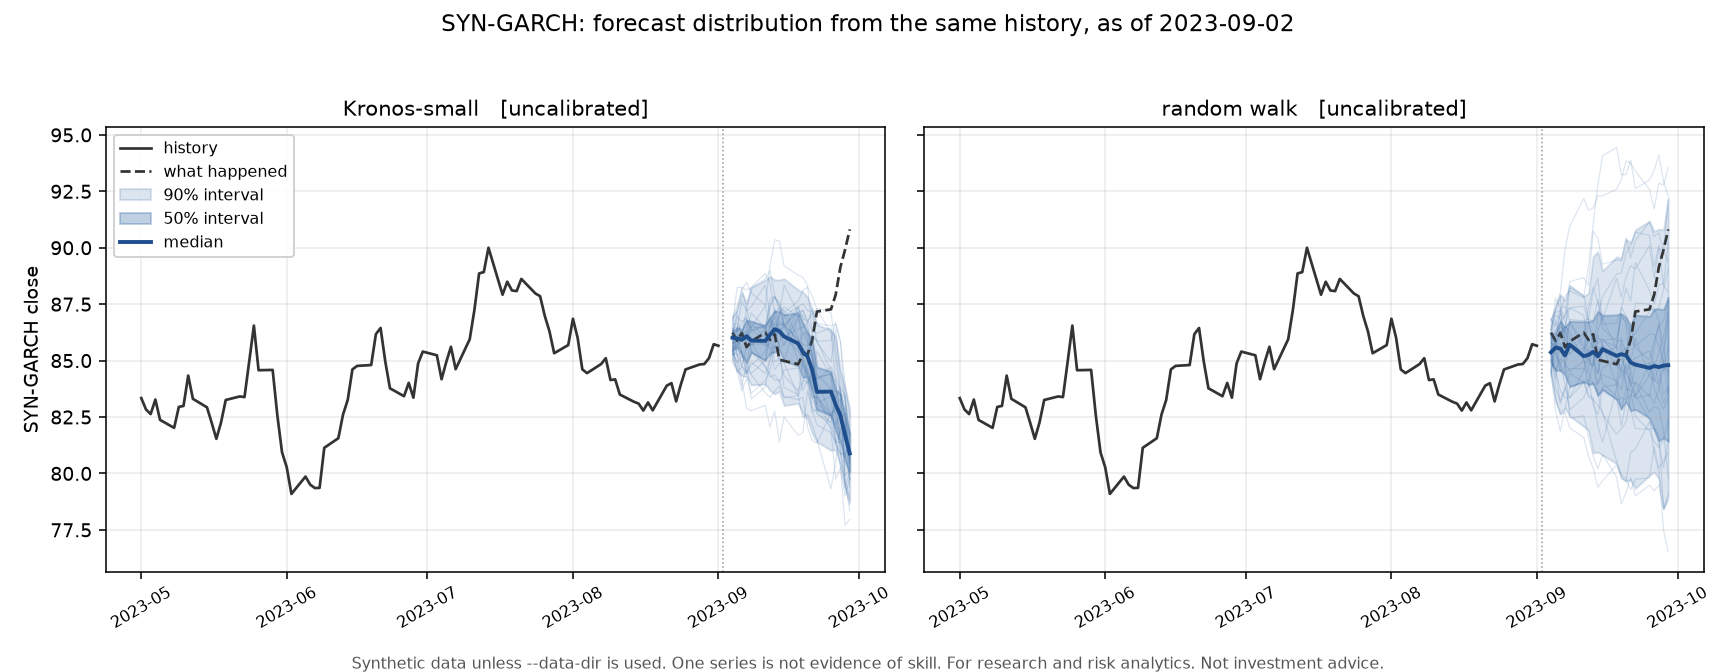
Conformal calibration with measured holdout coverage, a regime-weighted ensemble, a risk layer and a leakage-guarded walk-forward evaluation are built. On the bundled synthetic series no model is distinguishable from the random walk, and the leaderboard says so. Multi-asset portfolio risk is always uncalibrated. See calibration, risk and the benchmark methodology.
Start here
| Page | What is in it |
|---|---|
| Methodology | How calibration, routing, risk translation and evaluation are meant to work, and what we refuse to claim. |
| Safety and compliance | Point-in-time discipline, no live execution, untrusted external text, data licensing. |
| Model cards | One card per forecaster: source, licence, training data, limitations, calibration status. |
| ADR 0001 | Why Apache-2.0 plus a proprietary ee/, and where the line sits. |
| ADR 0002 | Why Kronos is vendored, and why its sampler is replaced. |
| ADR 0003 | The two-clock data model and the forecast contract. |
Install
pip install tycheon                  # core: baselines, calibration, risk, backtest
pip install "tycheon[kronos]"        # Kronos + torch
pip install "tycheon[timesfm]"       # TimesFM
pip install "tycheon[chronos]"       # Chronos
pip install "tycheon[serve]"         # FastAPI + MCP server
Development setup, the dev stack and the contribution gate are in
CONTRIBUTING.md.
The three invariants
Everything in this project follows from these.
- Point-in-time. Every data read takes an
as_ofand refuses anything published after it. Leakage tests are mandatory for every data path. - Uncertainty is not optional. Every forecast carries intervals or
quantiles, calibration status, the model mix that produced it, its
as_ofand a model card reference. - Honest baselines. Every evaluation reports the random-walk baseline and a Diebold-Mariano test, published whichever way the result goes.
What Tycheon is not
- Not a consumer trade-signal product.
- Not personalized investment advice.
- Not a market-data vendor. Providers are pluggable and you bring your own data licence; Tycheon never redistributes licensed exchange data.
- Not a live execution system. v1 is paper and simulation only, and only through Keelgate-governed tools.
For research and risk analytics. Not investment advice. Nothing produced by this software is a recommendation to buy or sell any security. Past calibration does not guarantee future coverage.